
Cboe Quant Conference 2026
Examine the Future of Quantitative Finance
Cboe Global Markets at The Old Post Office
2026 Speakers & Keynotes
Featured speakers scheduled for this event:
Fabio Mercurio
Emanuel Derman
Oleg Bondarenko
Sebastien Bossu
Hans Buehler
Antoine Jacquier
Florian Bourgey
Henry Schwartz
Florian Huchedé
Ashley Whitfield
Mathieu Rosenbaum
JJ Kinahan
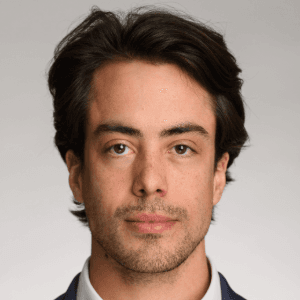
Fabricio Vieira
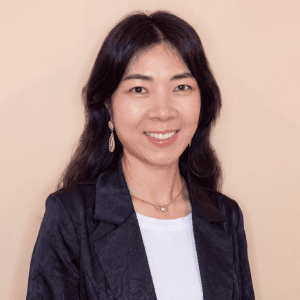
Yuying Chen
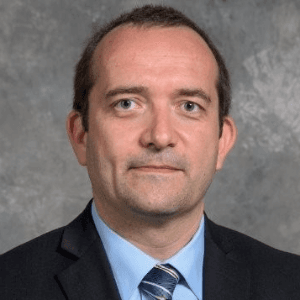
Dobrislav Dobrev
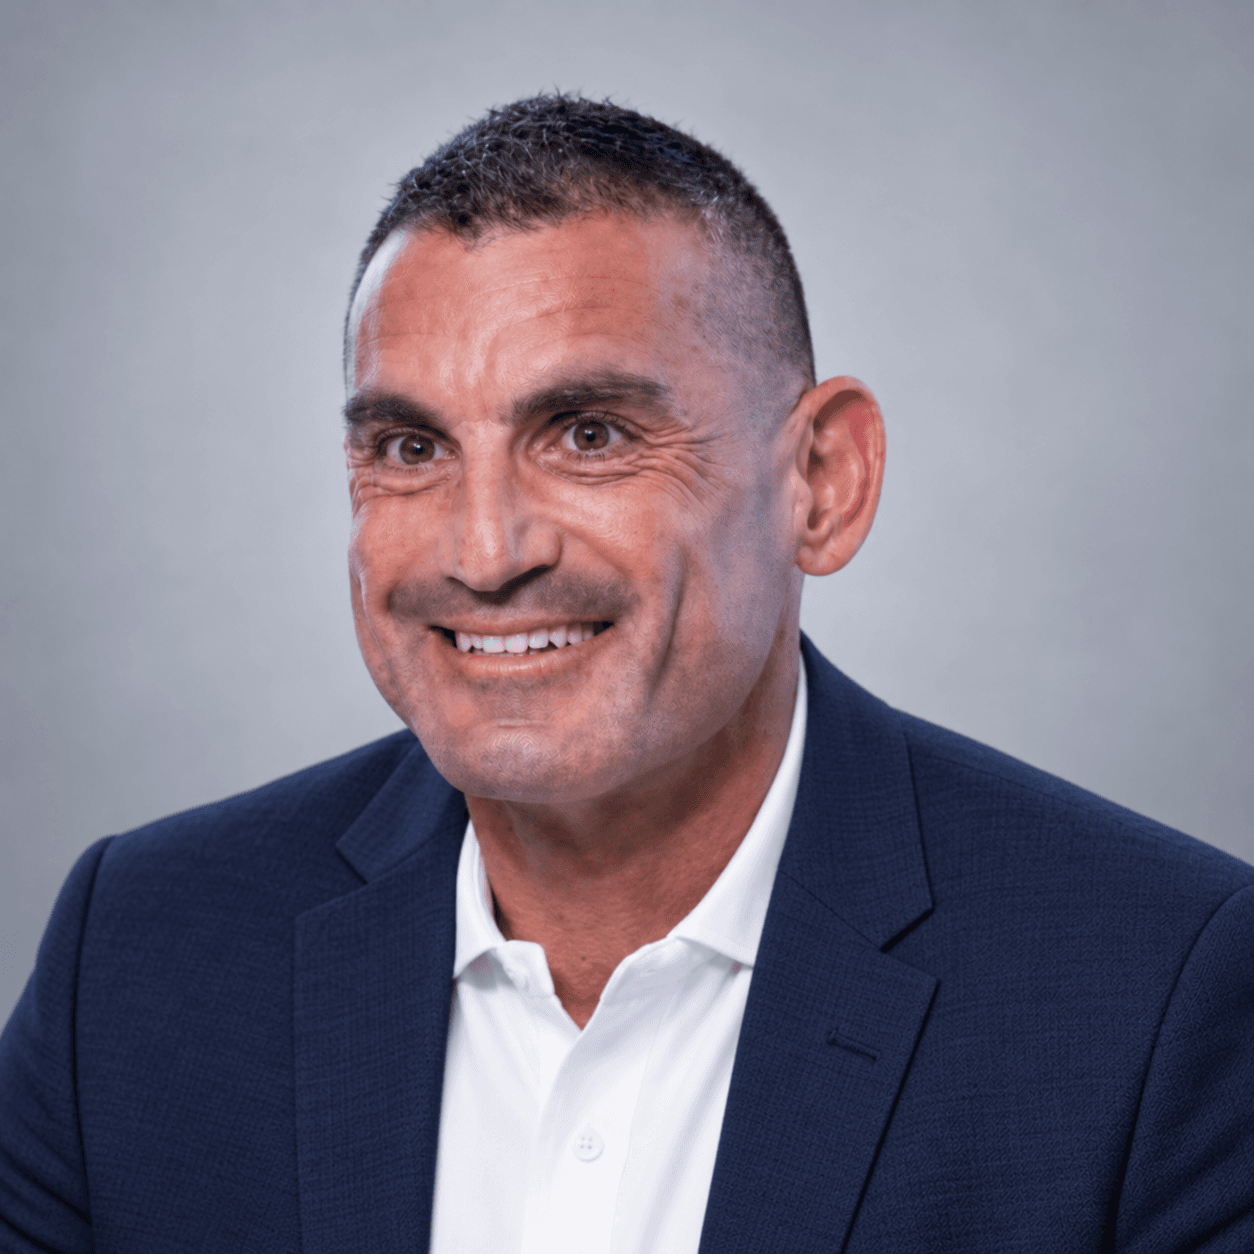
David Dooman
John Hiatt
Rob Hocking
Please Join Us
We've gathered thought leaders from academia and industry to examine the future of quantitative finance with a special focus on:
SPX Volatility & VIX Trading - Advanced strategies for futures, options, and options on futures
SPX/VIX Joint Pricing Models - Innovative approaches to Equity options modeling
Variance Trading Innovations - Latest developments in variance futures and replication
Market Microstructure Analysis - Deep dives into options market measure
Designed specifically for quantitative practitioners from volatility arbitrage specialists, investment banks, market makers, and volatility asset managers. With keynote speakers: Professor Emanuel Derman, Professor of Practice Emeritus at Columbia University and Fabio Mercurio, Global Head of Quantitative Analytics at Bloomberg.
This event is for industry participants only and is closed to the media. For media inquiries, please contact institutionalmarketing@cboe.com.
Cboe Global Markets at The Old Post Office
EXAMINE THE FUTURE OF FINANCE